Guide · insurance
How insurance works on a covered loss.
Direct billing, the documentation your adjuster needs, and your right to choose your own contractor, explained plainly.
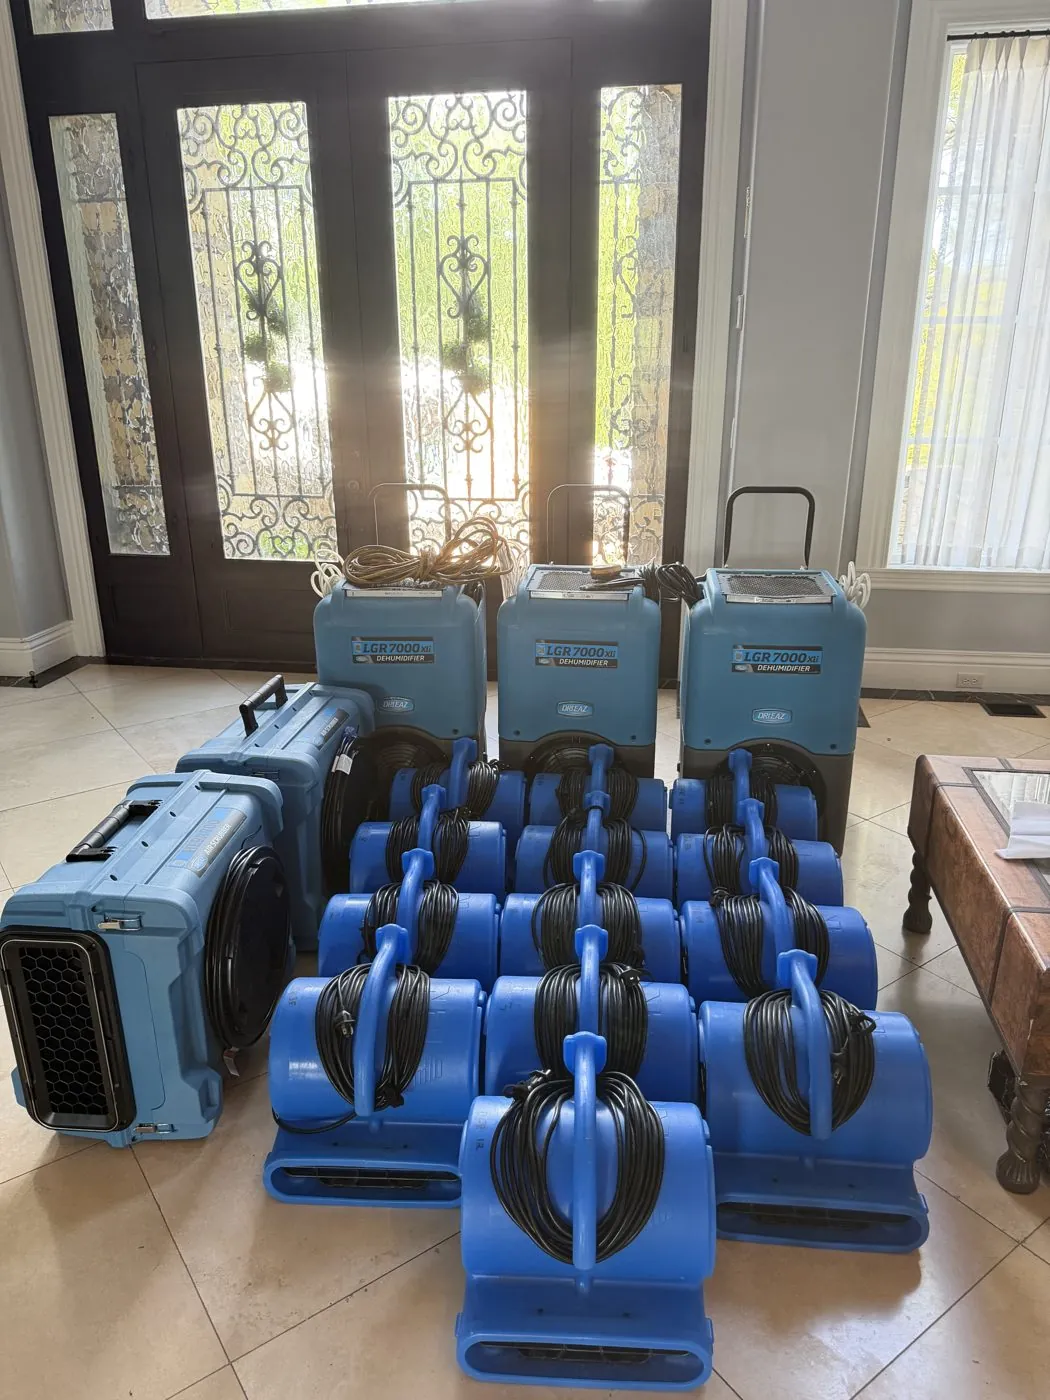
Drying equipment staged for a water loss
Direct billing, the documentation your adjuster needs, and your right to choose your own contractor, explained plainly.
A water, fire or storm loss is stressful enough without trying to figure out the claim on your own. Here’s how it works when Nitro is on the job.
Your adjuster and your policy make the final call on coverage. Our job is to document the damage accurately and do the work right, either way.
Call us early. Policies have time limits for reporting a loss, and claims get denied when too much time goes by with no steps taken to stop the damage. Our free inspection shows you what’s actually wet and whether it’s worth a claim.
No. As the policyholder you can choose any contractor you want. When you hire us, we represent you, not the insurance company.
Yes, for covered losses, and we provide the readings, photos and scope carriers ask for. We have no carrier affiliations.
Not for an emergency dry-out on an insurance claim. We get your claim started and bill your insurance company directly.
That’s your call and it doesn’t change the assessment. Plenty of people pay out of pocket because the deductible math doesn’t work in their favor. We’ll scope it either way.
Yes. Wait too long and the carrier can deny the claim as pre-existing damage, lack of maintenance, or no steps taken to prevent further damage. As the policyholder you have an obligation to mitigate. When in doubt, have it looked at early.
Generally, when wind is the cause. Water coming through a worn-out roof with no wind damage is much harder to get covered. Rising groundwater from outside the house usually isn’t covered without separate flood insurance. A pipe that breaks inside the house usually is. Your policy and adjuster make the final call.
Tell us how to reach you and we'll call you back to talk through what happened, and whether you actually need restoration.
Water actively coming in? Don't wait on a form. Call now, phones are answered 24/7.
(918) 550-2555